
A Cooling Market Might Be a First Home Buyer's Window

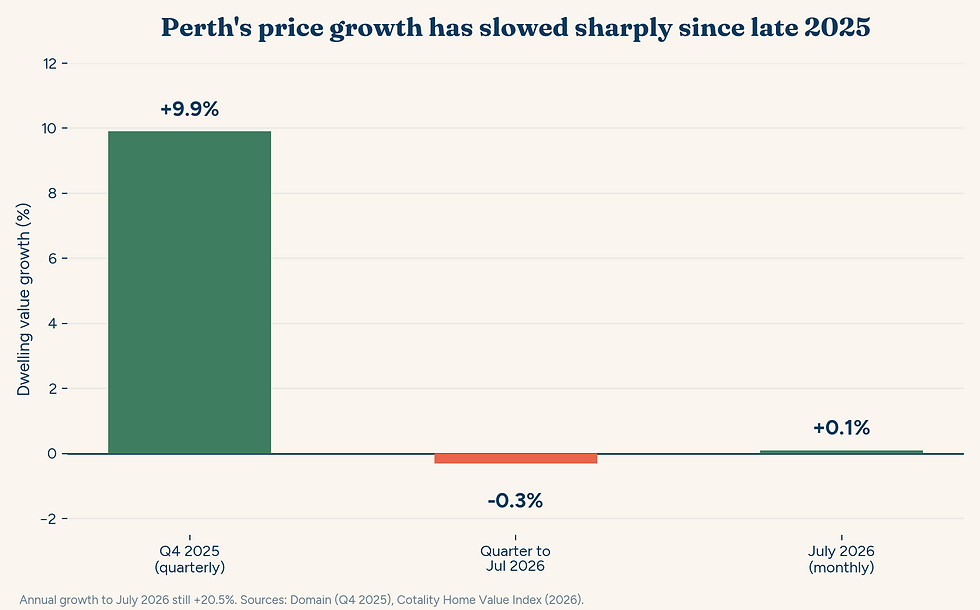
If you've been priced out of the market over the past few years, the current slowdown is worth a second look. Buyer competition has genuinely eased — even if not every part of the puzzle has gotten easier.
Less competition at every open home
Ray White, which tracks around 13,000 open homes a week nationally, reports that the average number of people attending an open home has dropped from around four a year ago to about two now. Its chief economist points to “uncertainty” as the dominant theme in the market right now — buyers are still out there, just far less aggressively.
For a first home buyer, that matters more than a small drop in price. Less competition means less pressure to overbid, more room to negotiate on price and conditions, and more time to make a considered decision instead of a rushed one.
The scheme cap, revisited
The federal Home Guarantee Scheme (also known as the First Home Guarantee) lets eligible buyers purchase with just a 5% deposit and no Lenders Mortgage Insurance. The property price caps were significantly increased from 1 October 2025 — in Perth, the cap now sits at $850,000; in regional WA, it's $600,000.
That's a big shift from the old $600,000 Perth cap. Perth's median unit price (around $650,000) now sits comfortably under the new cap, and even the median house price — over $1.09 million — is a lot closer to being in range than it used to be, even though it still sits above the threshold.
Home Guarantee Scheme (from 1 Oct 2025) | Detail |
|---|---|
Deposit required | 5%, with no LMI |
Income caps | None |
Annual place limits | None |
Perth metro price cap | $850,000 |
Regional WA price cap | $600,000 |
Why competition has eased
Part of the softer buyer turnout comes from investors stepping back. Recent changes affecting negative gearing and capital gains tax settings have cooled investor demand nationally — which, in practice, means fewer cashed-up bidders competing against first home buyers for the same properties.
“Less competition often matters more than waiting for the exact bottom.”
What hasn't changed
A cooling market doesn't remove every hurdle. A few things still apply exactly as they did a year ago:
You still need genuine savings and a clean serviceability picture to get approved.
APRA's 3-percentage-point serviceability buffer still tests your ability to repay at your rate plus 3%.
A softer national market doesn't guarantee a lower price in the specific suburb you want.
The takeaway
Timing a market bottom perfectly is close to impossible — by the time it's obvious prices have turned, the best opportunities have usually already gone. What's measurable right now is that competition has eased and the tools available to first home buyers (the 5% deposit scheme in particular) haven't gone anywhere. That combination is worth acting on rather than waiting out.
Let's check your borrowing power
I'll walk you through the First Home Guarantee, what you can actually afford, and whether now suits your timeline — no cost, no obligation.
Ian Freeman · Finance 365 ian@finance365.com.au · 0439 365 365 ianfreemanfinance.com.au
Credit Representative Number 439731 of Australian Credit Licence 384704.